· ReadyStack
Worked example
Real numbers from this tool, line by line.
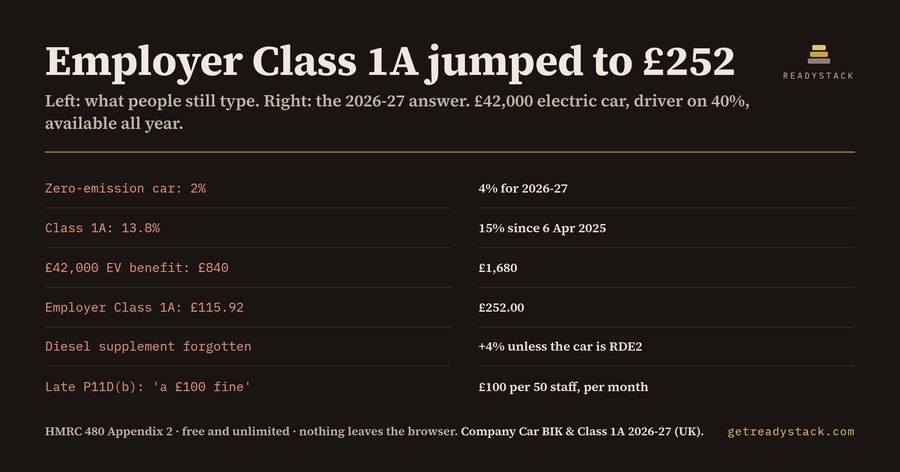
Six lines on a UK 2026-27 P11D(b) are still being typed from last year's table, and on a single £42,000 electric company car they add £136.08 of employer Class 1A that nobody budgeted for. The payroll manager reading a rate sheet written in 2024 sends that return to HMRC by 6 July 2027, and it is wrong before anyone checks it.
Two numbers moved, and they moved away from how most people remember them.
The first is the appropriate percentage for a zero-emission car. It sat at 2% from 2020-21 through 2024-25, went to 3% for 2025-26, and is 4% for 2026-27. HMRC's 480 Appendix 2 table for 2026-27 reads 4% at 0 g/km, then five electric-range bands for cars at 1 to 50 g/km (4% at 130 miles or more of electric range, then 7%, 10%, 14% and 16% as the range falls), then 17% at 51-54 g/km rising one point for every additional 5 g/km, capped at 37%.
The second is Class 1A National Insurance. The employer rate was 13.8% until 5 April 2025. From 6 April 2025 it is 15%, and it is 15% for 2026-27. Class 1A is the employer's charge on the taxable value of the benefit, and unlike secondary Class 1 on salary it is not reduced by the Employment Allowance.
Put both through one ordinary car. A £42,000 pure electric company car, driver on the 40% rate, available all year, no capital contribution:
- 2024-25 rates: 2% of £42,000 is £840, and 13.8% of £840 is £115.92 of employer Class 1A.
- 2026-27 rates: 4% of £42,000 is £1,680, and 15% of £1,680 is £252.00 of employer Class 1A.
That is £136.08 more on one car per year, or £756 across a three-year lease. The driver's tax moved too: £672 a year at 40% instead of £336.
The petrol and diesel side is where it gets quietly expensive. A 120 g/km petrol car at the same £42,000 list price sits at 31% for 2026-27 — 17% for the 51-54 band plus one point for each of the fourteen 5 g/km steps up to 120. That is a £13,020 cash equivalent and £1,953 of Class 1A. Make it a diesel that misses the RDE2 standard and the supplement is 4%, taking it to 35%, a £14,700 benefit and £2,205 of Class 1A. RDE2-certified diesels are exempt, and nothing pushes the percentage above the 37% cap.
Two reducers get dropped by hand. An employee capital contribution cuts the list price used in the calculation, but only up to £5,000: type £8,000 and only £5,000 counts. Days the car was genuinely unavailable pro-rate the benefit. The same £42,000 EV with a £5,000 contribution and 90 days unavailable gives a £1,115.07 cash equivalent and £167.26 of Class 1A, not £252.
Then the deadline. P11D and P11D(b) for 2026-27 are due by 6 July 2027, and the Class 1A must be paid by 22 July 2027. The late-filing penalty is not a flat £100: it is £100 per 50 employees, or part of 50, for each month or part month the return is late. Twelve employees is £100 a month. A hundred and twenty is £300 a month.
The extension takes ten figures about the car, the driver and the payroll, and returns the 2026-27 percentage, the cash equivalent, the driver's tax, Class 1A at 15%, the 2024-25 comparison, the three-year total and the monthly late-filing exposure — in a browser popup or a free web page, with nothing sent anywhere.
That is free, for as many cars as you like, no key and no locked answers. The $60 licence adds a different axis: it saves each car as a .csv working paper you keep, and reminds you 30, 14 and 1 days before the filing date. UK accountancy fee guides for 2026 put P11D benefits reporting at £30 to £75 per employee.
Check one car against the table before the return goes in. The percentage you half-remember is two years old.
Questions people ask
What does this actually work out?
It takes a car's P11D list price, CO₂ figure and electric range and returns the 2026-27 appropriate percentage, the cash equivalent, the driver's income tax at 20%, 40% or 45%, and the employer's Class 1A National Insurance at 15%. It also shows the late P11D(b) penalty: £100 per 50 employees, or part of 50, for every month the return is late.
Who is this for?
UK payroll managers, fleet administrators and owner-directors of small limited companies who have to put company cars on a P11D and settle the Class 1A on the P11D(b). It is built for the person checking a figure before 6 July, not for a tax adviser rebuilding a whole fleet schedule.
Why not just ask a chatbot or use a free rate sheet?
Most still quote 2% for a zero-emission car and 13.8% for Class 1A. Both ended on 5 April 2025: the zero-emission percentage is 4% for 2026-27 and Class 1A is 15%. Published sheets also disagree on the diesel supplement, which is 4%, and they rarely apply the £5,000 capital contribution cap.
What is free and what needs a licence key?
Every calculation is free and unlimited, with no key, no watermark and no locked answers, in both the browser popup and the free web page. The $60 licence adds two things on a different axis: saving each car as a .csv working paper you keep, and P11D(b) deadline reminders 30 days, 14 days and one day out.
What would this cost if someone else did it?
UK accountancy fee guides for 2026 put P11D benefits reporting at roughly £30 to £75 per employee, charged as an add-on to payroll. Fully managed payroll including P11D processing runs £12 to £25 per employee per month. The licence is $60 once, for one person or team seat,.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.